Attention: homeowners
Free 20-minute live session
Make your mortgagetax deductible
Most homeowners pay their mortgage with after-tax dollars and invest whatever is left over. Debt conversion changes that order, with the same monthly payment you're already making.
▶ Watch this first, then save your seat below
Master Your Mortgage
Inside the strategy that converts your mortgage into a tax-deductible loan, with the exact same monthly payment you're already making.
A cash-flow strategy Canadian homeowners have used for decades.
Next live session: Wednesday evening · 20 minutes on Zoom · free, with Q&A
Register for the free session below
You'll get the Zoom link by email, plus a reminder before it starts.
Who should join
Homeowners who want their mortgage working for them
Turn your mortgage into good debt
Put the payment you already make to work converting your mortgage into deductible investment debt.
A tax-efficient mortgage
How the interest on your home loan can slowly become interest that may be deductible.
Build wealth on the side
Grow an investment portfolio alongside the conversion, without new money from your budget.
Your own numbers
See it modelled on your balance, rate and tax bracket, not a generic calculator.
How the money moves
Same payment. Different debt.
- You make your regular paymentThe same mortgage payment you make today. Nothing extra comes out of your budget.
- The principal reopensWith a readvanceable mortgage, every dollar of principal you pay comes back as room on a linked line of credit.
- That room gets investedInterest on money borrowed to earn investment income may be tax-deductible.
- The refund goes back on the mortgageYour tax refund goes back on the mortgage as a lump sum, so it converts to deductible debt faster.
Your total debt follows your regular payments. What changes is what that debt is for.
Before you register
This works best for:
- Homeowners 10 to 15 years from retirement
- No company pension to count on
- Real equity in your home
- Already investing something each month
- A steady income
Probably not a fit: less than about 20% equity, or you can't qualify for a readvanceable mortgage; anyone uncomfortable investing borrowed money; planning to sell in the next few years; you need every dollar of monthly cash flow.
What you'll learn
Inside the 20-minute session
- Why a $500,000 mortgage takes about $1.6 million of your payThe after-tax math nobody shows you at signing.
- How a readvanceable mortgage reopens every dollar you pay downYour principal becomes room you can put to work.
- How that room can be invested so the interest may become deductibleAnd why the refund goes straight back on your mortgage.
- The accelerators that can cut the conversion from about 21 years to about 12Debt swaps, cash flow diversion and more.
- Who it fits, who it doesn't, and what to ask your accountantSo you leave knowing whether it is worth a closer look.
The example from the session
Same mortgage. Two outcomes.
Illustrative only, not typical, not a guarantee, not a real client. Assumes a $520,000 mortgage at about 4.5%, a 25-year amortization, a 43% tax bracket and a 7% return.
Your host
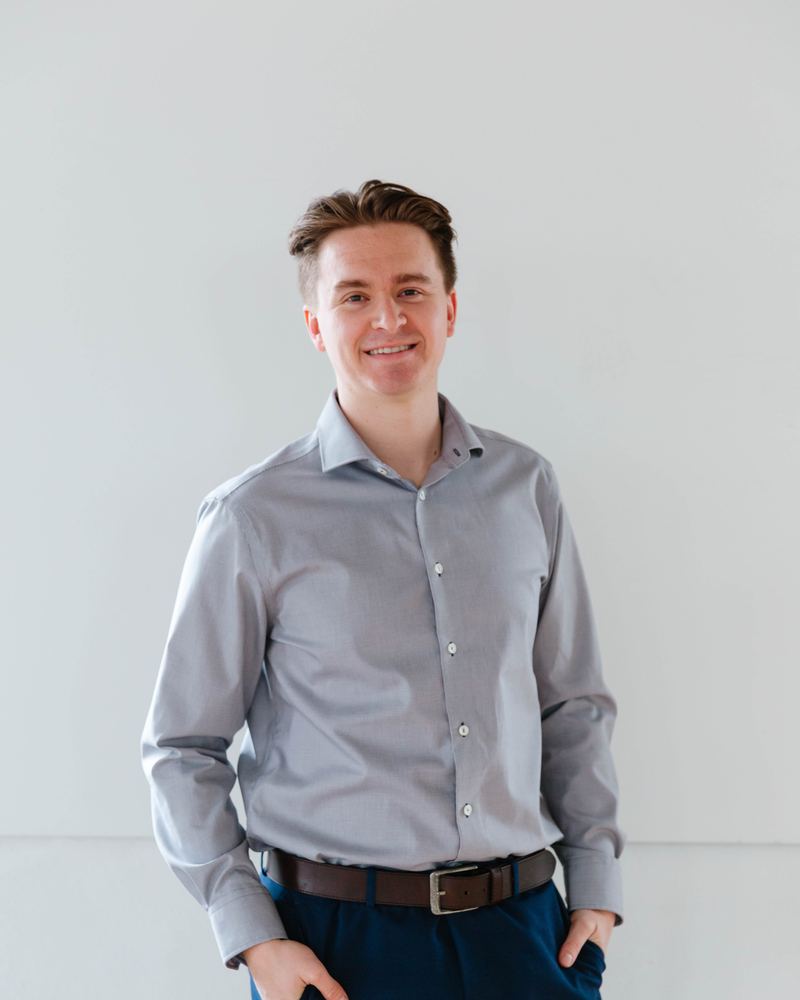
Jonah Hoyos
Most people are taught to chase the lowest rate. The bigger number is how your mortgage is structured.
I work in the mortgage industry, and I'll be honest: most Canadians are overpaying on their mortgage, and nobody tells them. We spend years in school and never learn how a mortgage actually works.
I run these strategies on my own home, and I've helped families across Canada save hundreds of thousands in interest. This session is the short version of what I wish every homeowner knew.
Make your mortgage work for you.
After you sign up
From the session to your own plan
- Step 1Watch the sessionTwenty minutes live on a Wednesday evening, or the recording whenever suits you.
- Step 2Book a callWe look at your own balance, rate and tax bracket and see what the strategy could do for you.
- Step 3Get it set upI arrange the right mortgage structure and show you how to run it month to month.
FAQ
Common questions
Is it really free?
Yes. It is a 20-minute teaching session, and nothing is sold at the end. If you want your own numbers afterwards, you can book a call.
Will there be a replay?
Yes. If you can't make it live, you can watch the recording of my free training anytime.
Is this legal?
Yes. It is built on a long-standing CRA principle: interest on money borrowed to earn investment income may be deductible. How the money is used is what matters, and you'll confirm your setup with your accountant.
Do I need to prepare anything?
No. It helps to know your rough mortgage balance, your renewal date and your tax bracket.
I already understand it. Can I skip ahead?
Yes. Book a call and we will look at your numbers directly.
Ready to make your mortgage work for you?
Save a seat for a Wednesday evening. Twenty minutes, plain language, real numbers, and time for your questions.
Reserve my free seat →